2024.11 Comprehensive Housing Price Index

Note
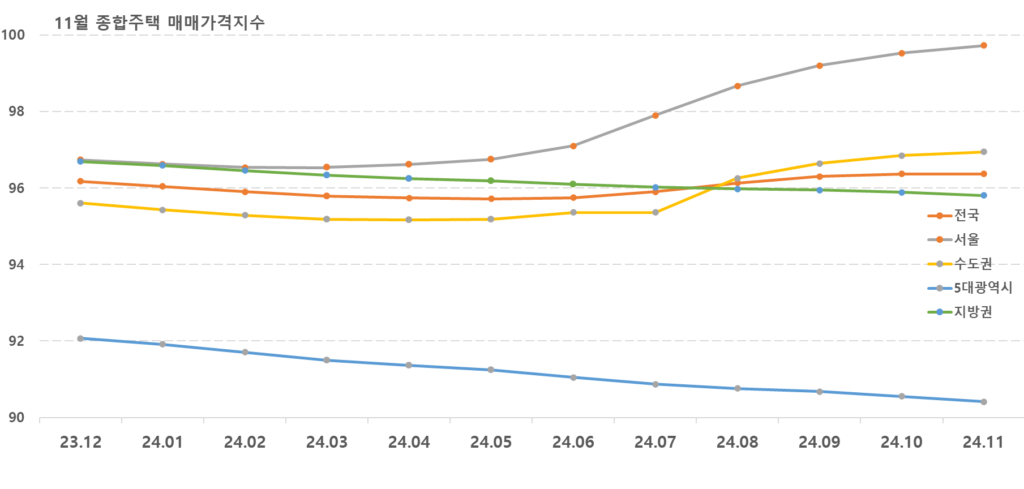
The comprehensive housing transaction price index rose in the metropolitan area and Seoul, and ended with a decline in the five metropolitan cities and local areas. The number of rising areas (101 → 83) decreased significantly compared to the previous month, the number of flat areas (3 → 3) remained unchanged, and the number of falling areas (74 → 88) increased significantly, so that the rise nationwide stopped and ended with a flat trend. In Seoul, some preferred complexes are showing a localized upward trend, but other complexes are continuing to wait and see due to market uncertainties such as loan regulations, and the increase rate has decreased compared to last month. Incheon showed a mixed trend by complex, turning from an increase to a decrease, and Gyeonggi showed an increase mainly in areas with good living conditions.
In Seoul (0.33%), the rise was led by Wangsimni and Eungbong-dong in Seongdong-gu (0.39%), major complexes in Ichon and Hannam-dong in Yongsan-gu (0.34%), and complexes near subway stations in Gongdeok and Ahyeon-dong in Mapo-gu (0.31%) toward the north of the river. In the south of the river, the rise was led by complexes under reconstruction in Apgujeong-dong and Gaepo-dong in Gangnam-gu (0.55%), and major complexes in Banpo and Seocho-dong in Seocho-gu (0.35%). In Incheon (-0.06%), the rise was led by Cheongna-dong and Wondang-dong in Seo-gu (0.21%), which have good living conditions, but Michuhol-gu (-0.30) fell due to the impact of new housing stock. Gyeonggi Province (0.08%) saw an increase in Anyang Dongan-gu (0.47%) and Gwacheon-si (0.36%) due to expectations of reconstruction, but Icheon-si (-.034%) saw a large decrease due to the continued impact of unsold properties. It appears that the upward trend is changing to a downward trend as transaction volume has fallen significantly nationwide and properties are piling up.

Note
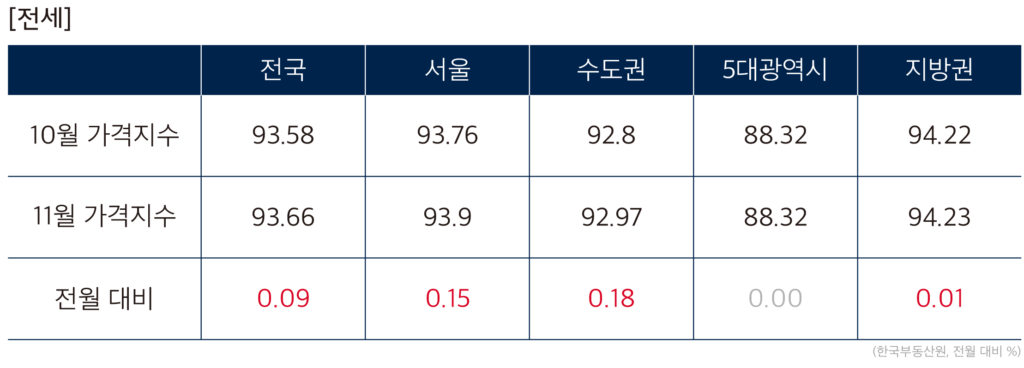
The jeonse price index also continued to rise while the five metropolitan cities and local areas remained flat. It has been continuously rising since June of last year, and in the case of Seoul and the metropolitan area, it has risen for 17 consecutive months, but the increase was reduced nationwide (0.17%), rising by 0.09%. The number of areas increasing (128→124) slightly decreased compared to the previous month, the number of areas remaining flat (3→4) increased, and the number of areas decreasing (47→50) increased slightly. In the Seoul area, jeonse prices have been steadily maintained centered on preferred complexes, but the increase has been reduced compared to last month due to the burden of loans and fatigue from the price increases so far. Incheon continued to be affected by the lack of supply, and Bupyeong and Seo-gu were the main areas, while Gyeonggi Province rose mainly in Guri and Namyangju, which have good transportation environments.
In Seoul (0.30%), Gangbuk led the rise centered on major complexes in Nowon-gu (0.34%) and Jung-gu (0.31%), while Gangnam saw the largest increase centered on Gangnam-gu (0.40%) and Yeongdeungpo-gu (0.,28%). Among the five metropolitan cities, Daegu (-0.16%) saw the largest decline, but Gwangju (0.11%) finished the day sideways as it rose centered on areas with good living conditions.


Note
The monthly rent price index rose slightly by 0.08% compared to the previous month. In Seoul, due to the influence of loan regulations, there is a steady demand for monthly rent changes, and the index rose mainly in preferred complexes with good living conditions. In Incheon, it rose mainly in Bupyeong-gu and Michuhol-gu, and in Gyeonggi, it rose mainly in Siheung and Seongnam, which have good transportation accessibility. Among the five metropolitan cities, the index fell mainly in Nam and Jung-gu in Daegu, but Ulsan rose notably, turning from a decline to an increase. In other regions, Jeju and Jeonnam continued to decline, but Gyeongnam saw an increase, and Sejong also turned upward, and 8 provinces maintained an increase.
Compared to July and August, when housing market transaction volume was strong, transaction volume has fallen significantly, and with the recent political uncertainty and turmoil, further increases in sale prices appear limited. However, as rental demand continues to increase, the monthly rent price index is expected to continue to show a gradual increase.