Today, we will look at the revised tax laws for 2026, especially those related to housing.
First, the ‘special application of housing acquisition in population-declining areas’ is expanded.
The special exemption for housing acquisition in population-declining areas refers to a system that applies the tax exemption for one house per household to the existing house when a single-home owner acquires a house located in an area with population declining.
If this special provision applies, transfer prices up to KRW 1.2 billion are exempt from housing transfer taxes and, depending on the holding period, can receive a "long-term holding special deduction" of up to KRW 80%. Furthermore, when calculating comprehensive real estate tax, the basic deduction of KRW 1.2 billion plus the senior citizen and long-term holding tax deduction of up to KRW 80% can be applied.
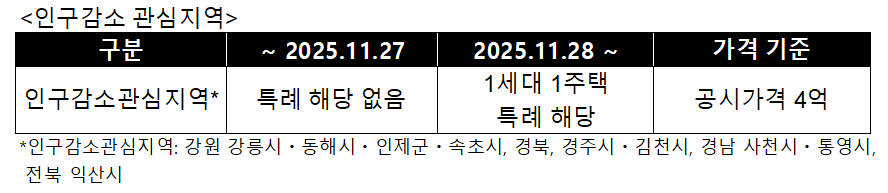
Previously, the requirement was limited to only ‘areas with population decline’, but now ‘areas of concern for population decline’ has been added in accordance with Article 2, Paragraph 12-2 of the Special Act on Local Autonomy and Balanced Regional Development.
The above special provisions can be applied to houses acquired after November 28, 2025 in the 'area of interest'.

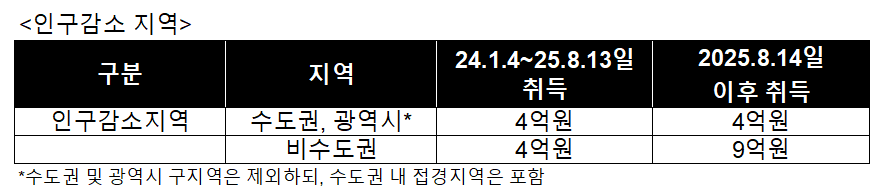
The second is ‘increasing the special price requirements for housing acquisition in areas with declining population.’
This means that when applying the first special exception above, the previously applicable area was 400 million won, but after the revision, the public price remained at 400 million won or less in the metropolitan area (only some areas such as border areas) and was raised to 900 million won or less in non-metropolitan areas.
 The change will apply to those who acquire after August 14, 2025, and houses acquired between January 4, 2024 and August 13, 2025, regardless of whether they are in the metropolitan area or outside the metropolitan area, will be subject to the existing regulations only if the assessed value is KRW 400 million or less.
For reference, the standard for the assessed housing price in 'areas of concern for population decline', where special application was added on November 28, 2025, is 400 million won.
Thirdly, the extension of the special application period for the transfer tax on rural housing, etc.
There was already a law that provided for a tax exemption on the transfer of a home owned prior to acquisition, such as a rural home, if the home was held for three years or more. This law has now extended the deadline for this exemption to December 31, 2028.
finish
In this way, the revised 2026 tax law further refines the criteria for home ownership and disposal, based on region and conditions. More important than the existence of special provisions is the fact that the application of these provisions varies depending on when the home was acquired and the region it falls within. Even for the same home transaction, if the timing is not accurately determined, benefits can disappear, leaving only the tax burden.
In particular, regulations related to population decline areas, areas of concern for population decline, and rural housing require careful review, as they are highly likely to be applied in practice. Once tax laws are revised, all subsequent revisions must adhere to the new standards. Ultimately, the most realistic tax-saving strategy is to accurately understand the revised system and adapt it to your current holdings and plans.